Lumen Vietnam Fund

Blog

Vietnam and ASEAN move to elevate position in global value chain

Vietnam and ASEAN move to elevate position in global value chain

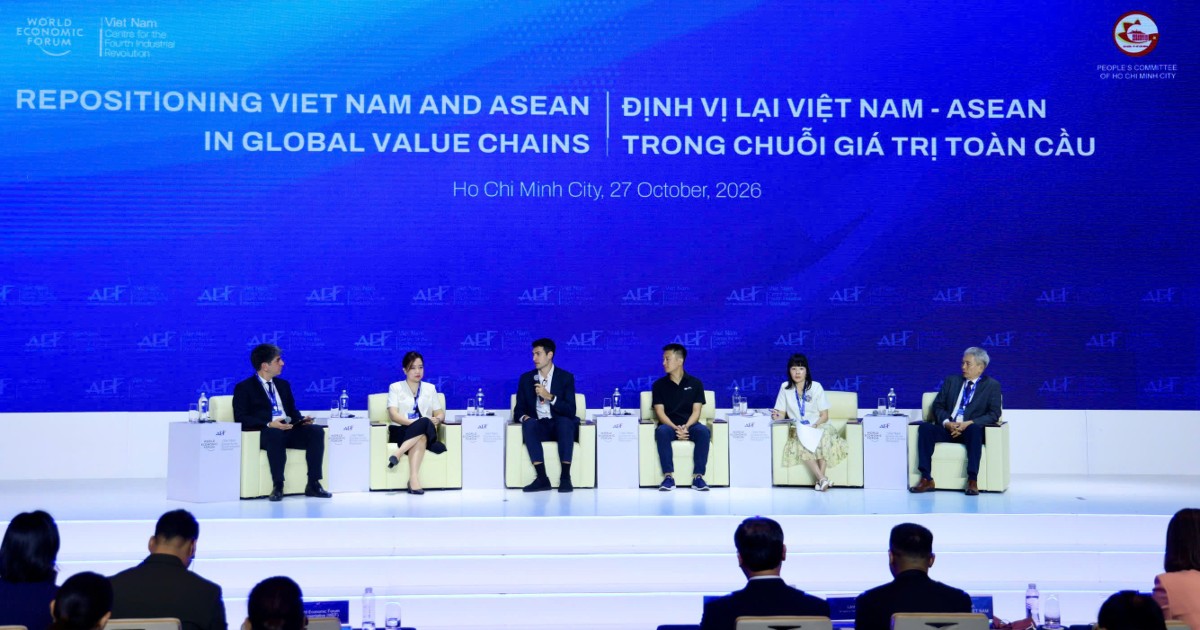
At the Autumn Economic Forum 2026 on October 27, Vietnamese and international experts shared experiences to help ASEAN and Vietnam not only attract foreign direct investment (FDI) but also retain higher added value from production and export activities.

During the discussion session “Repositioning Vietnam - ASEAN in Global Value Chains” on October 27, co-organized by the World Economic Forum (WEF) and the Fourth Industrial Revolution Center in Vietnam (C4IR), in the framework of the Autumn Economic Forum 2026 in Ho Chị Minh City, representatives from businesses, international organizations, and regulatory agencies pointed out that attracting investment in the ASEAN region is just the beginning.

The greater challenge is how domestic enterprises can participate more deeply in the regional production network, enhance added value, and better utilize the capital and technology flows moving into ASEAN.

ASEAN attracts investors but internal connectivity remains limited

According to Mr. Kyriakos Triantafyllidis, Head of Growth and Strategy, Centre for Advanced Manufacturing and Supply Chains, under the World Economic Forum (WEF), ASEAN currently has about 700 million people, with a combined economic scale of $4.3 trillion. By 2025, the region was expected to attract $245 billion in FDI, a 10 percent increase from the previous year.

The proportion of foreign-origin value in Vietnam's exports increased from about 33 percent in 2010 to nearly 50 percent in 2022. This indicates that Vietnam's exports are increasingly dependent on imported materials, components, and inputs.

To create more value domestically, Vietnam needs to enhance the capacity of local enterprises to participate more deeply in supply chains and become tier-1 suppliers for FDI corporations. On a regional scale, intra-ASEAN trade accounts for only about one-fifth of the region's total trade turnover, indicating that member economies still have significant room to strengthen connectivity and production cooperation.

These issues require ASEAN not only to continue attracting investment and expanding exports but also to develop the capacity of local enterprises, strengthen supply chain links within the region, and participate more deeply in high-value stages such as technology, design, and product innovation.

Expert perspectives on trade and investment potential

Mr. Sacha Dray, an Economist at the World Bank in Economic Policy Unit for Vietnam, agreed that ASEAN has a favorable foundation for trade and investment development, with abundant labor, high trade openness, and an extensive network of trade agreements. However, the region has not yet fully exploited the benefits of integration.

In terms of production, ASEAN has deeply participated in the global value chain, from automobile and electric vehicle production in Thailand, assembly in Vietnam, to semiconductor manufacturing, testing, and packaging in Malaysia and Singapore. However, the intra-regional value chain remains limited: global value chain participation based on regional links accounts for only about one-third in ASEAN, compared to 70 percent in the EU.

Specifically, of ASEAN’s total export turnover of about $2 trillion, only 22 percent is consumed within the region, compared to about 60 percent in the EU. This makes ASEAN economies more dependent on external demand, while also limiting the ability to spread benefits among countries in the region.

According to Mr. Dre, the income disparity among member countries - where the gap between the poorest and richest nation reaches up to 70 times, compared to eight times in the EU- also creates uneven market demand and resource allocation. To bridge this gap, he suggested increasing cross-border investment among ASEAN countries, connecting foreign enterprises with local suppliers, and removing non-tariff barriers.

Business views on ASEAN’s appeal

From a business perspective, Ms. Jessica Nguyen, General Director, Country Holding Officer, and Board Chairwoman of ABB Vietnam, believes that ASEAN’s appeal comes from three factors: market size; increasingly developed production capacity; and regional connectivity.

According to her, ASEAN no longer competes solely on low labor costs. Evidence is that Vietnam, Thailand, Malaysia, and Indonesia are investing more in advanced manufacturing, digitization, and developing technical human resources. At the same time, trade agreements and regional connectivity allow businesses to build supply chains across multiple countries instead of being limited to a single market.

Trust in the supply chain is built through quality, traceability, reliability, and product consistency. These are the conditions for Vietnamese suppliers to transition from fulfilling orders to becoming partners with higher technical and management capabilities.

However, after more than 32 years of operation in Vietnam, ABB observed that technology and machinery can be acquired relatively quickly, whereas operational and management capabilities take time to build. “The long-term value that multinational corporations bring is not just automation equipment, but also operational knowledge, global standards, and the ability to build resilient supply chains,”Ms. Nguyen emphasized.

Policy recommendations for supplier development

From a state management perspective, Ms. Pham Quynh Mai, Deputy Director General of the Multilateral Trade Policy Department under the Ministry of Industry and Trade, noted that reducing tariffs is not enough to promote regional trade. ASEAN countries need to address behind-the-border barriers, including customs procedures, standards, certifications, logistics, and differences in rules of origin among trade agreements.

According to her, the time and costs incurred at each stage, from sourcing materials, organizing production, meeting rules of origin to transportation and delivery, all affect the efficiency of the entire supply chain. Therefore, ASEAN needs to enhance information exchange, improve enforcement capacity, and limit the duplication of inspection and certification procedures.

For Vietnam, she proposed building a national supplier development program involving the Ministry of Industry and Trade, local governments, industry associations, and FDI enterprises. This program would help small and medium-sized enterprises access finance for technology investment, production upgrades, and workforce training.

The Autumn Economic Forum 2026, themed “The Convergence of New Global Growth Poles,” took place from October 26 to October 29 in Ho Chi Minh City, directed by Prime Minister Le Minh Hung and chaired by the Ho Chi Minh City People’s Committee in collaboration with C4IR.


Source: Nhu Quỳnh
Latest Posts

Vietnam holds 71 billion-ton CO2 storage potential, unlocking CCUS opportunities in oil and gas

Vietnam holds 71 billion-ton CO2 storage potential, unlocking CCUS opportunities in oil and gas

Vietnam is considered a country with immense potential to develop CCS and CCUS across its petroleum industry, especially via offshore carbon geological storage

Carbon capture and storage (CCS), as well as carbon capture, utilization, and storage (CCUS) technologies, are increasingly recognized as vital pathways in emissions reduction—particularly for hard-to-abate industrial sectors.

Vietnam is considered a country with immense potential to develop CCS and CCUS across its petroleum industry, especially via offshore carbon geological storage. According to assessments, the country possesses among the greatest CO2 storage capacities in Southeast Asia, with a potential of up to 71 billion tonnes of CO2 concentrated primarily across three geological regions…

Speaking at the workshop "Carbon Capture, Utilization, and Storage (CCUS) Technologies: Solutions to Accelerate Net Zero in Vietnam" on October 27, Dr. Nguyen Huu Luong, Senior Expert at the Vietnam Petroleum Institute, noted that current global operational CCUS capacity remains relatively modest, with approximately 64 million tonnes of CO2 being captured.

However, global CCS deployment is forecast to expand rapidly, surging nearly tenfold by 2030 to surpass 500 million tonnes per year.

Globally, there are 77 CCUS projects in commercial operation and 610 under various stages of development, with an anticipated average compound growth rate of nearly 40% through 2030. Key geological formations utilized worldwide for CO2 storage include depleted oil and gas reservoirs, deep saline aquifers, and unminable deep coal seams.

To date, cumulative global injected and stored CO2 stands at around 380 million tonnes.

"This is an extremely modest figure against a theoretical global capacity exceeding 10 trillion tonnes of CO2, demonstrating enormous headroom for growth in this sector," Dr. Luong said.

The International Energy Agency (IEA) has concluded that reaching Net Zero emissions by 2050—moved forward from the previous 2070 horizon—will require an additional 50% expansion in CCUS deployment. In 2023, the IEA also underscored CCUS as an indispensable, mandatory component to achieve Net Zero targets.

For Vietnam, joint research conducted by Petrovietnam (PVN) and the Japan Organization for Metals and Energy Security (JOGMEC) identified Vietnam as possessing among the highest CO2 storage potentials in Southeast Asia, estimated at approximately 71 billion tonnes. This storage capacity is concentrated primarily in three offshore sedimentary basins: the Song Hong Basin (39 billion tonnes), the Nam Con Son Basin (22 billion tonnes), and the Cuu Long Basin (10 billion tonnes). Crucially, Vietnam could capitalize on over 1 billion tonnes of effective storage capacity within depleted oil and gas fields alone.

Vietnam also holds distinct competitive advantages for CCUS, including 34 offshore oil and gas fields whose storage suitability has been preliminarily evaluated by Petrovietnam. Notably, in 2011, Vietnam became the first nation in Southeast Asia to successfully implement CO2 enhanced oil recovery (EOR) injection at the Rang Dong field.

CCUS scope in Vietnam’s decarbonization roadmap

Addressing the workshop, Deputy Minister of Agriculture and Environment Le Trong Yen emphasized that achieving Vietnam’s Net Zero emissions commitment by 2050 necessitates profound transformation across economic growth models—particularly as Vietnam targets ambitious double-digit GDP expansion—as well as production methods and natural resource utilization.

According to the Deputy Minister, this transition must run parallel with ensuring national energy security, ecological integrity, and industrial competitiveness while creating fresh development impetus. Every mitigation solution must be evaluated on scientific rigor, economic feasibility, and Vietnam’s unique practical conditions.

To lay the groundwork for real-world deployment, Mr. Yen called for clearly defining the specific role, positioning, and application scope of CCUS within Vietnam's national decarbonization roadmap. Concurrently, technical standards, scientific benchmarks, and safety protocols across the entire CCUS value chain must be thoroughly clarified.

Industry specialists noted that Vietnam has already established baseline prerequisites for CCUS development. The country possesses concentrated point-source CO2 emissions from power generation and heavy industries, vast offshore geological storage capacity in sedimentary basins and depleted fields, and mature oil and gas expertise, seismic data, and infrastructure that can be repurposed for CO2 transport, injection, and long-term storage.

Furthermore, the gradual emergence of a domestic carbon market, green finance frameworks, and legal improvements governing petroleum operations provide foundational momentum for CCUS execution.

Most notably, the amended Petroleum Law (Law No 10/2026/QH16), adopted by the National Assembly on August 23, 2026, and taking effect on March 1, 2027, introduced specific legal provisions governing carbon capture and storage operations linked to petroleum activities, establishing an initial regulatory cornerstone for field deployment.

Dr. Nguyen Thanh Tung, Deputy Director of the Vietnam Petroleum Institute, assessed that incorporating CCUS provisions into the revised Petroleum Law is a decisive milestone, providing the legal basis to transition from exploratory research toward commercial projects.

However, Dr. Tung stressed that to commercialize CCS/CCUS on an industrial scale, Vietnam must establish comprehensive guidelines covering the full project lifecycle: acreage block awards, investor selection, site characterization, injection licensing, operational monitoring, site closure, and post-closure long-term liability frameworks.

From an international perspective, delegates concluded that under appropriate market conditions, CCS/CCUS provides critical decarbonization pathways for hard-to-abate industries, spurs technological innovation, and enhances the export competitiveness of low-carbon goods. The degree to which mitigation credits are monetized on carbon markets will ultimately hinge on robust legal architectures, baseline carbon accounting methodologies, and stringent measurement, reporting, and verification (MRV) protocols.


Vietnam needs integrated solutions to accelerate clean energy transition: experts

Vietnam needs integrated solutions to accelerate clean energy transition: experts

Vietnam’s favourable conditions for expanding clean energy sources, however, the energy transition still faces significant challenges.

Vietnam’s solar and wind power capacity has expanded significantly, with the two sources accounting for approximately 19% and 7% of the country’s electricity mix, respectively, in 2025, according to Ms. Nguyen Thi Thu Huyen of the Institute of Energy under the Ministry of Industry and Trade.

Speaking at the recent “Clean Energy for a New Era of Growth” forum, Ms. Huyen said the figures highlighted the increasingly important role of renewable energy in Vietnam’s power sector.

Vietnam has favourable conditions for expanding clean energy sources, including onshore and offshore wind, rooftop solar, biomass and emerging energy technologies. Under power development planning scenarios, solar power capacity could reach hundreds of thousands of megawatts, while offshore wind capacity could exceed 100,000MW by 2050.

However, the energy transition faces significant challenges. Growing electricity demand from data centres, artificial intelligence and electrified transport requires reliable, stable and affordable power supplies. Meanwhile, the existing transmission grid, dispatch capabilities and energy storage infrastructure have yet to keep pace with these demands.

Experts at the forum proposed a range of long-term solutions. Dr Vo Tri Thanh, Director of the Institute for Brand and Competitiveness Strategy Research, stressed that the transition to clean energy must follow a roadmap suited to Vietnam’s economic development. Adjustments to power planning should take into account implementation capacity, access to partners and the ability to master technology.

He also highlighted the need for coordinated efforts to address policy and regulatory challenges, mobilise investment, develop energy infrastructure, strengthen technological capabilities and train highly skilled workers.

Dr Mai Duy Thien, Chairman of the Vietnam Clean Energy Association, said expanding clean energy required more than simply increasing power generation capacity. Instead, a comprehensive approach was needed, integrating planning, transmission, distribution, demand-side management and financing.


Vietnamese exporters face dual challenge over power supply

Vietnamese exporters face dual challenge over power supply

Ensuring an adequate power supply remains critical as Vietnam's manufacturing and exports expand rapidly. However, some companies in global supply chains must also meet requirements on renewable electricity use and emissions. A draft amendment to Vietnam’s Electricity Law, now under consideration by the National Assembly, seeks to refine mechanisms to address these needs.

On October 20, at a working session of the National Assembly, the country's legislature, Minister of Industry and Trade Le Manh Hung presented a proposal to amend and supplement several provisions of the Electricity Law. The draft focuses on resolving bottlenecks in power generation and grid investment, while refining the framework for direct power purchase agreements (DPPAs) and renewable energy certificates.

The proposals come as businesses’ electricity needs evolve. National Assembly member Trinh Tu Anh, representing Lam Dong province, said many companies, particularly those participating in international supply chains, need not only reliable electricity at competitive prices but also proof of energy origin, renewable electricity usage, and emissions generated during production.

This presents the power sector with two parallel challenges: ensuring sufficient electricity to support economic growth and enabling businesses to access clean power and verify its use to meet customer requirements.

Reliable power supply remains an immediate priority

Vietnam’s manufacturing and export activities continued to expand strongly in the first nine months of 2026. Merchandise exports reached $434.3 billion, up 24.5% from a year earlier, according to the National Statistics Office. Industrial production rose 12.3%, while manufacturing and processing output increased 12.9%.

The expansion in manufacturing has been accompanied by a substantial rise in electricity demand.

The Ministry of Industry and Trade reported that commercial electricity consumption nationwide reached 237.19 billion kilowatt-hours (kWh) in the first nine months, up 9.66% year-on-year. Industry and construction accounted for 122.18 billion kWh, an increase of 8.32%, representing around 51.5% of total electricity sales.

Accounting for more than half of consumption, industry and construction remain the largest electricity-consuming sectors. For factories, a stable power supply is essential to keep production lines running, operate equipment and meet delivery schedules.

The ministry said the power system operated safely and reliably during the nine-month period, meeting demand from businesses and households. Maintaining supply over the longer term, however, will require coordinated development of generation capacity, transmission networks and grid dispatch capabilities.

According to Vietnam Electricity (EVN), total electricity generated and imported across the system reached 265.79 billion kWh in the first nine months. Coal-fired power contributed 132.63 billion kWh, or 49.9%, while hydropower generated 68.48 billion kWh, or 25.8%. Renewable energy sources, as classified by EVN, supplied 33.6 billion kWh, accounting for 12.6%. Gas-fired power contributed 20.48 billion kWh, while electricity imports totalled 10.3 billion kWh.

Hydropower output fell nearly 9% from a year earlier amid hydrological conditions affected by the El Niño phenomenon.

By contrast, coal- and gas-fired power together increased their share of total generation and imports to 57.6%, from 53.9% a year earlier, despite growth in other renewable energy sources. The shift towards a greater share of fossil fuels adds pressure to greenhouse gas emissions at a time when environmental requirements are becoming increasingly linked to manufacturing and export activities.

At the "Clean Energy for a New Era of Growth" forum held in Hanoi on October 27, Mai Duy Thien, chairman of the Vietnam Clean Energy Association, stressed the need to consider energy development in the context of economic growth and national competitiveness.

Clean energy development would not only help diversify supply but also enable businesses to adapt to increasingly stringent environmental standards, he said. This highlights the need to address energy security and the transition to cleaner electricity in parallel.

Clean electricity becomes a gateway to global supply chains

Renewable electricity requirements are already being incorporated into the supply-chain policies of multinational corporations, rather than remaining a trend expected to emerge in the future.

According to its 2026 Environmental Progress Report, Apple has incorporated a requirement for 100% renewable electricity into its Supplier Code of Conduct. The company requires its direct manufacturing supply chain to use 100% renewable electricity for Apple-related production by 2030.

According to the U.S. technology company, electricity consumption at supplier factories is the largest source of greenhouse gas emissions across its supply chain. Switching to renewable power is therefore a key component of its 2030 carbon neutrality goal.

Environmental requirements are also being considered as part of trade policy. In the United States, the proposed Clean Competition Act, introduced in Congress in December 2025, would establish a carbon border adjustment mechanism based on the emissions intensity of goods.

Meanwhile, the European Union entered the definitive phase of its Carbon Border Adjustment Mechanism (CBAM) on January 1, 2026, with the purchase and surrender of CBAM certificates scheduled to follow a phased timeline beginning in 2027. The mechanism covers products in six sectors: iron and steel, aluminium, cement, fertilizers, electricity and hydrogen.

Under the scheme, EU importers must fulfil obligations linked to emissions embedded in covered goods. Carbon costs could affect purchasing prices and the competitiveness of foreign producers, making emissions management an economic consideration as well as an environmental responsibility for businesses.

In Vietnam, demand for renewable electricity has already translated into actual transactions.

On June 1, 2026, Samsung Electronics Vietnam Thai Nguyen (SEVT) announced that it had implemented a direct power purchase agreement through the national grid, becoming the first corporate customer to complete a transaction under the DPPA mechanism.

The electricity supplied under the agreement comes from the TTC Duc Hue 2 solar power plant in Tay Ninh province, with expected output of around 70 million kWh a year.

The government established the DPPA framework under Decree 57/2025/ND-CP, which was subsequently amended and supplemented by Decree 243/2026/ND-CP. Current regulations have expanded participation to eligible electricity retailers operating in qualifying industrial and economic zones, creating additional arrangements for industrial customers to purchase renewable electricity.

Samsung’s case demonstrates that demand for renewable power has moved beyond commitments to actual transactions. It also raises questions about how the DPPA mechanism can be expanded to give more manufacturers access to clean electricity.

However, transactions conducted through the national grid require participants to account for network usage, dispatch, reserve capacity and other system services. How these costs are calculated and allocated directly affects companies’ overall electricity bills, as well as the interests of customers that do not participate in DPPAs.

This was among the issues the National Assembly’s Committee on Science, Technology and Environment called for clarification in its appraisal report on the draft Electricity Law amendments on October 20. The committee said DPPA participants should fulfil their cost obligations in full to prevent unreasonable cost transfers to other customers.

Beyond access to renewable electricity, businesses also need tools to verify the environmental attributes of the power they consume. Renewable energy certificates (RECs) serve this purpose, but their trading and use require reliable registration, verification and traceability mechanisms.

The draft amendments seek to establish a more complete legal framework for the REC market. The appraisal committee has called for clear rules on certificate ownership, trading and cancellation after use to prevent the same environmental attributes from being claimed more than once.

The issues under consideration therefore go beyond expanding the right to purchase renewable electricity. They also concern the overall cost of transactions and businesses’ ability to demonstrate that they use clean power - conditions that matter to companies seeking to meet environmental commitments made to international partners.

Reuters recently reported that the U.S.-China tariff war had helped accelerate the relocation of manufacturing to Vietnam. The expansion of export-oriented production has brought rising electricity demand. However, Reuters warned that the high share of coal-fired power in Vietnam’s electricity mix could pose an emissions challenge as international buyers increasingly scrutinize the carbon footprints of their supply chains.

For domestic companies seeking deeper integration into global supply chains, the ability to secure reliable electricity, manage emissions and meet partners’ environmental standards is likely to become increasingly important. These factors could increasingly influence the competitiveness of Vietnamese businesses as environmental requirements across global supply chains become more stringent.

See all blog